 MoneyStatsReport Editors
In this article
- How Your Adjustable-Rate Mortgage Rate Gets Calculated
- Why SOFR Replaced LIBOR as the Index
- Where SOFR and ARM Rates Stand in October 2026
- The Margin Is the Number You Can Shop
- How the Three Interest Rate Caps Limit a Reset
- What a Reset Could Look Like on a $400,000 Loan
- What to Check Before Your First Adjustment
- Frequently Asked Questions
- 1. Will a Lender Qualify Me at the Teaser Rate on an Adjustable-Rate Mortgage?
- 2. Do FHA Adjustable-Rate Mortgages Use SOFR and the Same Caps?
- 3. What Happens If SOFR Stops Being Published?
- 4. Can I Convert an Adjustable-Rate Mortgage to a Fixed Rate Without Refinancing?
- 5. Where Can I Look Up the SOFR Average My Lender Uses?
- The Two Lines That Still Decide Your Payment
In the mid-2000s, adjustable-rate mortgage notes carried two lines that mattered more than the teaser rate. One named the index, often six-month LIBOR. The other named the margin.
Borrowers tended to know their starting rate by heart, yet few could name either number. Two decades later, the index has a new name, SOFR, and the Federal Reserve has raised rates for the first time since 2023.
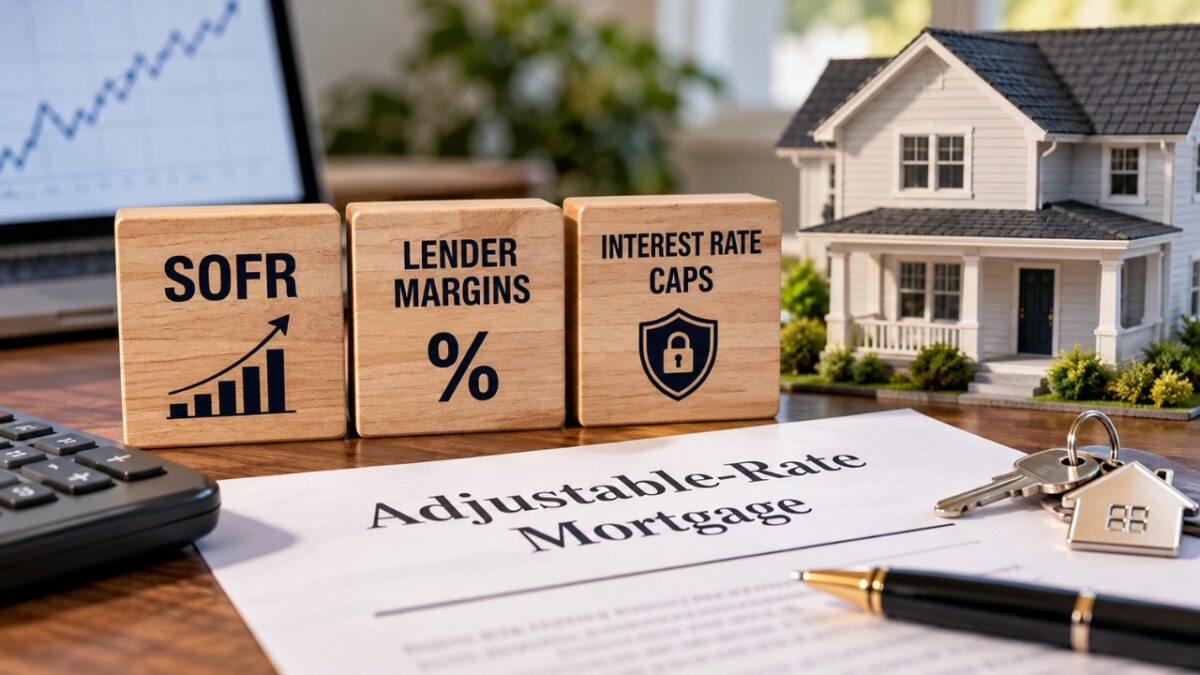
Your adjustable-rate mortgage payment after the fixed period still comes down to that index, plus a margin that never moves, limited by three caps.
How Your Adjustable-Rate Mortgage Rate Gets Calculated
Once the fixed period ends, your adjustable-rate mortgage rate is rebuilt from three parts at every reset. SOFR, the index, supplies the moving piece.
The lender adds a margin that stays fixed after closing, as the Consumer Financial Protection Bureau explains in its note on how the index and margin work. Caps limit how far each reset can move.
A 30-day SOFR average of 3.82% plus a 2.75% margin equals 6.57%, which the Fannie Mae Selling Guide rules for ARMs round to the nearest one-eighth, or 6.625%.
If your loan started at 6.43% with a 2-point initial cap, the first reset cannot go above 8.43%. The rate also never falls below the margin, so your adjustable-rate mortgage has a basement.
A fully indexed rate is the index value plus the margin, rounded as your note requires. Caps decide whether you pay all of it at the next reset.
Why SOFR Replaced LIBOR as the Index
View this post on Instagram
LIBOR came from banks estimating what they would pay to borrow from one another. In 2005, nobody outside London could see a single trade behind the quote.
SOFR works differently. The New York Fed calculates the Secured Overnight Financing Rate as a volume-weighted median of actual overnight loans backed by Treasury securities, and it publishes the figure every business day. SOFR, in short, comes with receipts.
An adjustable-rate mortgage does not use the daily number. It uses a 30-day average, which smooths out a jumpy day at quarter-end. Fannie Mae began accepting SOFR loans on August 3, 2020, and it stopped buying new LIBOR loans by year-end.
Did you know? LIBOR panels ended after June 30, 2023, and a Federal Reserve rule under the LIBOR Act moved leftover contracts without workable fallback language to SOFR-based replacement rates.
Where SOFR and ARM Rates Stand in October 2026
On September 16 the Federal Reserve raised its target range by a quarter point to 3.75% to 4% in a 12 to 0 vote. SOFR followed, because overnight Treasury lending tracks the policy rate closely. I keep a notebook of figures for every piece, and these matter most for an adjustable-rate mortgage today.
Fed Lifts Range to 3.75%-4.00% — September 16, 2026
🔹 The Federal Reserve raised its target range to 3.75%-4.00% in a unanimous 12-0 vote, the first increase since July 2023.
🔹 Officials cited solid growth, a strong labor market and inflation still above the 2% goal, with geopolitical tensions and high energy prices in the mix.
🔹 The median forecast pointed to one more hike this year.
🔹 President Donald Trump called for cuts, saying the United States deserves ultra-low rates and criticizing trade deficits.
🔹 Fed Chair Kevin Warsh defended the decision as necessary for price stability.
🔹 Markets sold off, with the Dow Jones Industrial Average dropping more than 500 points.
#FederalReserve #FOMC #KevinWarsh #Trump #DowJones #Inflation #Rates #MarketTrends
— Markets Today (@marketsday) September 16, 2026
- The 30-day average SOFR stood at 3.81569% on October 9, 2026.
- The weekly MBA application survey put the 5/1 ARM contract rate at 6.43% with 1.69 points for the week ending October 2.
- In that same week, the 30-year fixed conforming rate averaged 7.49%.
- Adjustable-rate mortgages made up 10.3% of all applications.
Fixed rates climbed first, as we covered when 30-year mortgage rates moved back above 7%. Where SOFR goes next is anyone’s guess, and this article will not pretend to know.
The Margin Is the Number You Can Shop
SOFR is the same for every borrower on a given day. Margins are not. The lender picks the margin, writes it into your note, and it stays there for the life of the adjustable-rate mortgage.
We tested the difference.
At the October 9 SOFR average, a 2.75% margin produces a fully indexed rate of 6.625% after rounding. A 3% margin produces 6.875%. On a loan with about $374,000 left after five years, the reset payment differs by roughly $59 a month, or about $709 a year, for each year the loan adjusts.
Home equity lines run on the same index-plus-margin logic, which we walked through when HELOC rates posted their biggest jump of 2026. Ask for the margin in writing next to the teaser rate. A quarter point is not nothing.
How the Three Interest Rate Caps Limit a Reset
Caps are the guardrails on an adjustable-rate mortgage, and they arrive written as three numbers. The lender program sheets we checked for this piece pair a 2/1/5 structure with 5/6 SOFR loans and 5/1/5 with 7/6 and 10/6 loans.
The CFPB consumer handbook on adjustable-rate mortgages shows where the same limits appear on your Loan Estimate.
- The initial cap limits the first adjustment after the fixed period ends.
- The periodic cap limits every later adjustment, which comes every six months on a /6 loan.
- The lifetime cap limits the total rise above your starting rate.
One overlooked rule cuts the other way. On Fannie Mae plans, per-adjustment caps apply to decreases too, so a 1-point periodic cap also slows how fast your rate can fall. Lifetime caps apply only to increases. Guardrails, it turns out, run on both sides of the road.
What a Reset Could Look Like on a $400,000 Loan
We ran a hypothetical 5/6 adjustable-rate mortgage through Reset Day. The loan is $400,000 on a 30-year schedule at the 6.43% MBA rate, with a 2.75% margin and 2/1/5 caps.
Principal and interest start at $2,509.89, and after 60 payments the balance is $374,140.98.
| SOFR at first reset | Fully indexed rate | Rate after caps | New monthly payment | Change |
| Unchanged, 3.82% | 6.625% | 6.625% | $2,555.53 | Up $45.64 |
| 1 point higher, 4.82% | 7.625% | 7.625% | $2,795.36 | Up $285.47 |
| 2 points higher, 5.82% | 8.625% | 8.43% | $2,995.06 | Up $485.17 |
| 1.5 points lower, 2.32% | 5.125% | 5.125% | $2,214.53 | Down $295.36 |
The first row surprises people. With SOFR flat, the payment still rises because 6.43% sits below the 6.625% fully indexed rate. In row three, the 2-point initial cap absorbs the extra 0.195 points, and the lifetime cap keeps the rate at or below 11.43%.
None of the rows is a forecast, and taxes and insurance are left out.
What to Check Before Your First Adjustment
Federal rules give you time. Under Regulation Z section 1026.20, your servicer must send a separate notice 210 to 240 days before the first payment at the new rate, then 60 to 120 days before each later payment change.
The first notice must also list alternatives, including refinancing, selling, and loan modification.
- Find the index, margin, and all three caps in your adjustable-rate mortgage note.
- Check the lookback. Fannie Mae loans use the index value available 45 days before the change date.
- Calculate your own fully indexed rate with the latest SOFR average.
- Compare that rate with current fixed quotes, including points.
- Price a refinance before the notice lands, not after.
Reading the index, margin, and caps in a mortgage note takes less time than watching a Fed press conference.
Frequently Asked Questions
1. Will a Lender Qualify Me at the Teaser Rate on an Adjustable-Rate Mortgage?
Not on a 5-year loan sold to Fannie Mae. Its qualifying payment requirements use the higher of the fully indexed rate or the note rate plus the first adjustment cap. Loans with longer fixed periods qualify at no less than the note rate.
2. Do FHA Adjustable-Rate Mortgages Use SOFR and the Same Caps?
FHA has allowed the 30-day average SOFR alongside the one-year Treasury index since a HUD rule effective March 31, 2023. Under HUD guidance on FHA ARMs, 5-year loans use 1/1/5 or 2/2/6 caps, while 7- and 10-year loans use 2/2/6.
3. What Happens If SOFR Stops Being Published?
Your note already plans for it. Fannie Mae requires lenders to disclose that a fallback index applies and how to monitor the index, the same switch LIBOR loans made in 2023.
4. Can I Convert an Adjustable-Rate Mortgage to a Fixed Rate Without Refinancing?
Only if your note includes a conversion option. On Fannie Mae plans, the fee is $250 when conversion is allowed monthly and $100 otherwise. A converted loan can no longer be assumed by a buyer.
5. Where Can I Look Up the SOFR Average My Lender Uses?
The New York Fed posts 30-, 90- and 180-day SOFR averages each business day around 8 a.m. Eastern. Use the average and lookback date your note names.
The Two Lines That Still Decide Your Payment
Too many borrowers have signed for a teaser rate without reading the two lines that decide their future payment. Those lines are still in every adjustable-rate mortgage note. Only the index changed its name.
Today, a 2.75% margin on top of a 3.82% SOFR average gives 6.57%. Many loan notes round that up to the nearest eighth of a point, which makes the fully indexed rate 6.625%, close to the 6.43% average 5/1 ARM rate.
If your fixed period ends within a year, pull your note this weekend, write down the margin and caps, and run the table above with your own balance.