 MoneyStatsReport Editors
In this article
- What the Fed Actually Counted as an Unpaid Bill
- Who Fell Behind Most Often
- The Bills People Let Slide First
- Sixteen Percent Missed, but 28% Struggled
- What People Did When the Money Ran Short
- Why Calling Before the Due Date Works
- Which Bills to Pay First When You Cannot Pay Them All
- Frequently Asked Questions
- 1. When Is the Next Fed Survey Due?
- 2. Does an Unpaid Utility Bill Hurt My Credit?
- 3. Did More Renters Fall Behind in 2025?
- 4. Do Newer Surveys Show the Same Pattern?
- 5. Where Can I Get Free Help?
- One Step to Take This Week
Picture a Friday at a credit union teller window. A member slides three bills and one paycheck across the counter and asks a simple question. Which bill can she skip?
The Federal Reserve now measures how many people face that same question. Sixteen percent of U.S. adults did not pay all their bills in full in the month before the Fed survey, which ran in late October 2025 and was published in May 2026. That is about one adult in six, close to the 17% reported for 2024.
What the Fed Actually Counted as an Unpaid Bill
The number comes from the economic hardships chapter of the Fed household report. According to the Fed description of the survey, Ipsos fielded it from October 17 to 28, 2025, and 12,934 adults made the final sample.
The definition matters more than the headline. A credit card counted as unpaid only when someone paid less than the minimum. Every other bill counted when it was not paid in full.
Did not pay in full, as the Fed uses it, means paying less than the minimum on a credit card or leaving any other bill partly or entirely unpaid in the prior month. It measures whether bills were paid in full, not whether they were paid on time.
So a headline claiming one in six Americans pays late reads the survey wrong. I read payment histories for eight years as an underwriter. Late and unpaid are different problems.
Who Fell Behind Most Often
Income explains most of the spread. Adults earning under $25,000 a year were almost five times as likely to leave a bill unpaid as adults earning $100,000 or more.
Group (2025 survey)
Did not pay all bills in full
Income under $25,000
34%
Income $25,000 to $49,999
26%
Income $50,000 to $99,999
13%
Income $100,000 or more
7%
Ages 18 to 29
24%
Ages 30 to 44
20%
Ages 45 to 59
16%
Ages 60 and older
9%
The Fed also found that 32% of Black adults and 25% of Hispanic adults left a bill unpaid, compared with 10% of white adults and 12% of Asian adults. Adults with a disability came in at 24%, against 14% without one.
Older adults often have steady Social Security deposits and smaller housing costs, which we suspect explains part of their low rate. That is my reading, not a Fed finding.
The Bills People Let Slide First
The 2025 report does not break unpaid bills down by type, so we went back one year. Fed figures for 2024 list the bills adults left unpaid most often.
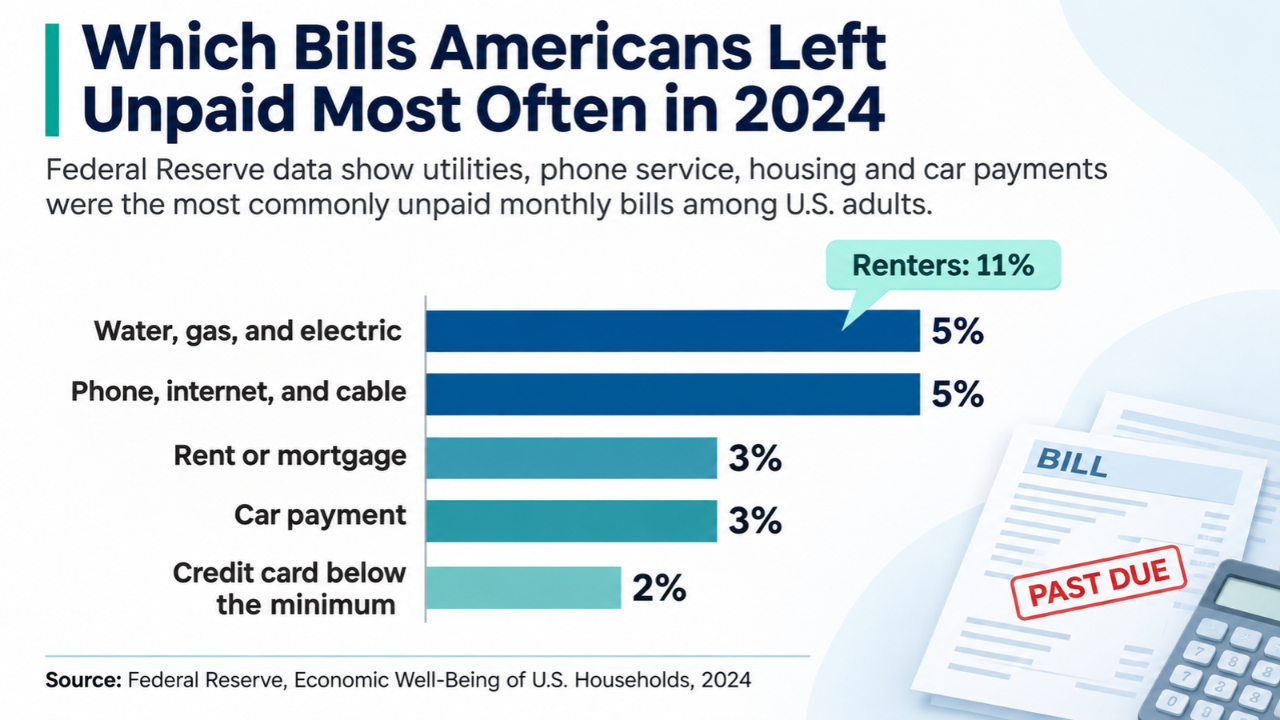
Renters carried most of the strain, 25% against 11% of homeowners. The Fed changed the question in 2023, so 17% for 2023, 17% for 2024, and 16% for 2025 are the only comparable years.
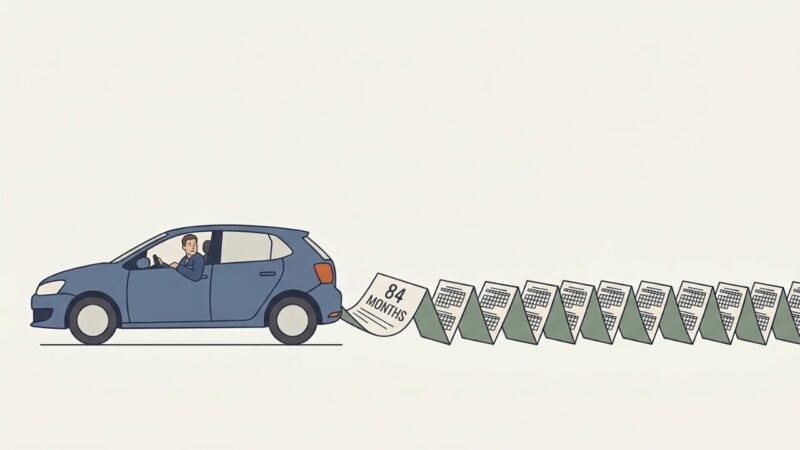
Car payments sit low on that list, but they are getting longer. A record share of new loans now runs 84 months or longer, which keeps one payment around for seven years.
A trade-in can add another burden. Our article on how old car debt gets added to a new loan shows why some buyers still pay for a vehicle they no longer own.
Sixteen Percent Missed, but 28% Struggled
New in 2025, the Fed also counted adults who paid every bill but had trouble doing it. Add them, and 28% of adults struggled with bills in the prior month. That 12-point gap worries me most, because nothing in a payment history shows the strain.
The Fed executive summary found that 63% of adults would cover a surprise $400 expense with cash or its equivalent, unchanged from 2024. Turn that around, and more than a third would not.
View this post on Instagram
Did you know? The Census estimate for July 1, 2025 puts the U.S. population near 341.8 million, with 21.1% under 18. That leaves about 270 million adults, so 16% equals roughly 43 million people. The 12-point gap equals about 32 million who paid everything and barely made it. Both figures are my estimates, not Fed counts.
What People Did When the Money Ran Short
Among adults who struggled, the most common response was cutting back on other spending, reported by 48%. The rest of the list shows how people bridge a gap without a cushion.
- 42% paid a bill late
- 23% used a credit card to pay over time
- 22% borrowed from friends or family
- 18% used savings or retirement money
The card route costs the most if it lingers, since card rates reached 21.19% in August.
In a Fed webinar on the 2025 survey, Fed economist Ellen Merry said about two-thirds of adults who struggled with bills could not cover a $500 expense from savings. A single car repair can push someone like that from the struggling group into the unpaid group.
Why Calling Before the Due Date Works
Consider two borrowers who lose the same overtime pay.
The first calls her auto lender before the due date, the lender agrees to move the date to match her paycheck, and her credit report shows no late payment.
The second stays quiet, and a 60-day late payment lands on his report. When he applies for his next loan, that mark can cost him a higher rate.
Utility and credit card payments received within 30 days of the due date typically do not affect your credit report. After 60 days, a credit card company may raise your interest rate.
That timing comes from a CFPB guide for people behind on bills, which also suggests matching due dates to payday. Calling early works because a lender has more options before an account goes delinquent. It is not a guarantee, and fees may still apply.
Which Bills to Pay First When You Cannot Pay Them All
The CFPB does not hand out one fixed ranking. Its worksheet groups bills by what you stand to lose, in roughly this order.
- Insurance, including the car coverage most states require and health coverage
- Anything you need to keep working, such as transportation and child care
- Housing and utilities, meaning rent or mortgage, property taxes, gas, electric, and water
- Other obligations, starting with court-ordered payments, then loans and credit cards
In 1981, when the mill cut shifts for my father, my mother kept the lights and the house payment current and let the department store card wait. She never saw a worksheet, but she followed the same logic.
Help exists for the middle of that list. The federal programs for utility and phone bills include LIHEAP for heating and cooling and Lifeline for discounted phone or internet service.
The Low Income Home Energy Assistance Program (LIHEAP) assists eligible households with their heating and cooling energy costs and energy-related home repairs. https://t.co/srAxX76G2R https://t.co/JPVDW4FcGN
— USAGov (@USAGov) October 24, 2024
Frequently Asked Questions
1. When Is the Next Fed Survey Due?
No date has been announced. The 2025 report came out on May 13, 2026, so spring 2027 would fit the pattern.
2. Does an Unpaid Utility Bill Hurt My Credit?
Usually not. The CFPB explains that most utilities do not report payment history, but a bill sent to collections can appear on your reports.
3. Did More Renters Fall Behind in 2025?
Yes. The full 2025 report found 23% of renters were behind on rent at some point in the year, up from 21% in 2024.
4. Do Newer Surveys Show the Same Pattern?
Mostly. Pew Research Center found in summer 2026 that 27% of adults cannot pay some or all bills in a typical month, using a different question.
5. Where Can I Get Free Help?
The CFPB lists HUD housing counselors at 800-569-4287 and the National Foundation for Credit Counseling at 800-388-2227.
One Step to Take This Week
Back at that teller window, there was no worksheet to hand the member, and no easy answer about which bill could wait. The Fed numbers suggest that about one adult in six faced a version of her choice in October 2025, and more than one in four felt the squeeze.
If you are in either group, take one step this week. Write your bills by due date next to your paydays, then call any lender whose date falls before your money arrives. A new due date costs nothing to request, and it can keep a late mark off your credit report.
This article is general information, not personal financial advice.