 MoneyStatsReport Editors
In this article
- What the New York Fed Actually Reported
- Why Mortgage Debt Fell, and Why That Isn’t the Story
- The Credit Card Number Is the One That Costs Money
- The Delinquency Headline You Should Read Twice
- Who Is Actually Feeling the Strain
- What You Should Do With These Numbers
- The Number We’d Tape to the Fridge
- Frequently Asked Questions
Thirteen point one trillion dollars in mortgages. One point two six trillion on credit cards.
Numbers that size are hard to feel, so we read them like a household’s bank statement.
A bank statement is basically a biography with decimal points, and this one says a lot about America in 2026. The big number is mostly calm.
The smaller one is where the money leaks out, every month, at more than 22% interest.
Here is what the New York Fed actually reported, and which headlines you can safely ignore.
What the New York Fed Actually Reported
On August 11, 2026, the New York Fed’s second-quarter household debt release put total household debt at $18.8 trillion. That was $13 billion lower than in the first quarter, a 0.1% dip, but $383 billion higher than a year earlier.
Mortgages make up about 70% of the total. Credit cards are under 7%. Here is the full picture as of June 30, 2026.
| Type of debt | Balance | Change from Q1 2026 | Change from Q2 2025 |
| Mortgages | $13.1 trillion | −$74 billion | +$182 billion |
| Auto loans | $1.71 trillion | +$28 billion | +$58 billion |
| Student loans | $1.65 trillion | −$7 billion | +$13 billion |
| Credit cards | $1.26 trillion | +$21 billion | +$54 billion |
| Home equity lines of credit | $459 billion | +$13 billion | +$48 billion |
| Other | $568 billion | +$6 billion | +$28 billion |
Auto loans hit a record. Credit cards sit just below their record of $1.28 trillion from late 2025.
One factor behind larger individual car loans is negative equity. Our report on old car debt rolled into new auto loans explains how a trade-in can leave buyers with more debt than the value of their new vehicle.
Why Mortgage Debt Fell, and Why That Isn’t the Story
A $74 billion drop in mortgage debt sounds like Americans paid down their homes. They didn’t. The full second-quarter report explains it plainly.
According to the New York Fed, the mortgage decline was “mostly due to a servicer transfer gap in the reporting of mortgages.” Without that gap, balances would have stayed roughly flat.
We’ve seen this from the inside. When a loan moves from one servicing company to another, the paperwork can go quiet for a month.
Borrowers occasionally called in a panic because their loan seemed to have vanished. It hadn’t. It was in transit.
So when you read that mortgage debt fell, treat it as a bookkeeping hiccup. That is definitely not a trend.
The real housing number to watch is home equity lines of credit, which rose for the 17th quarter in a row.
The Credit Card Number Is the One That Costs Money
Most mortgage debt is secured by houses and locked in at lower rates. Card debt has neither protection.
The Federal Reserve’s consumer credit release shows that accounts paying interest were charged an average of 22.15% in the second quarter of 2026. That is roughly three times the rate on a brand-new 30-year mortgage.
By August, that rate had reached 22.36%, as we explain in our latest credit card rates report.
View this post on Instagram
Consider a household carrying $19,400 in credit card debt, for example a balance build up after a divorce, a job loss, or a run of medical bills. At the current average card rate, a balance that size would cost about $4,300 a year in interest if it stayed at that level.
Three details from the report stand out:
- Card balances grew by $54 billion over the past year.
- Lenders raised credit limits by $85 billion in the quarter, which makes borrowing easier, not cheaper.
- The figures predate the September rate hike by the Federal Reserve, which pushed variable card rates higher.
The Delinquency Headline You Should Read Twice
Some headlines claim seriously late credit card balances nearly doubled since 2022. The number is real. The conclusion isn’t.
The share of card balances 90 or more days past due rose from 7.6% to 12.8% between late 2022 and early 2026. That figure counts old debts that lenders already wrote off years ago but still report to the credit bureaus.
New York Fed researchers untangled this in an analysis of the two diverging card delinquency measures. In 2004 through 2012, about 40% of charged-off debts still appeared on credit reports a year later.
By 2024, it was 80%. The rate at which balances newly turn seriously late, which is the better gauge of today’s stress, has been roughly stable for two years.
A lender charges off a card debt by removing it from its books after months of missed payments. The borrower still owes it.
Who Is Actually Feeling the Strain
Stable is not the same as fine. The New York Fed described new delinquencies for auto loans and credit cards as still elevated, and said it will keep monitoring them.
That is a warning, not a forecast of a crisis. The confirmed figures:
- About 6.97% of card balances transitioned into serious delinquency over the past year, versus 6.93% a year earlier.
- Auto loans moved from 2.93% to 3.00%.
- Mortgages rose from 1.29% to 1.52%, low but climbing.
- Overall, 4.7% of all household debt was in some stage of delinquency.
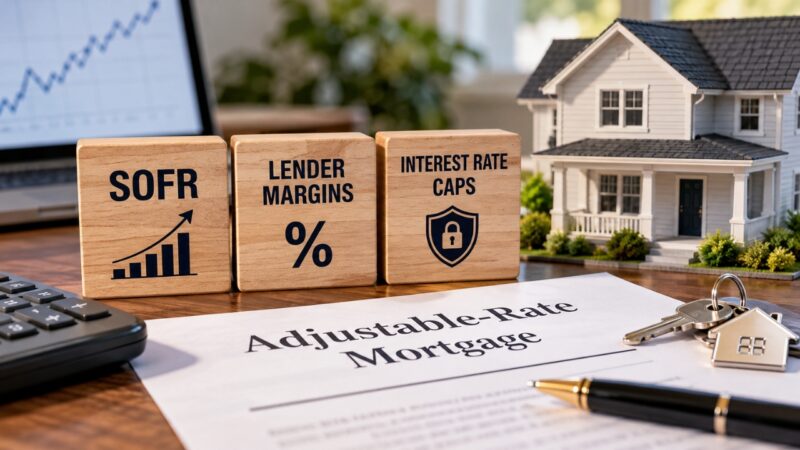
For homeowners with adjustable-rate loans, SOFR mortgage rates and interest rate caps help determine how much payments can change once the fixed period expires.
Mortgage Stress Is Rising Before The Labor Market Fully Breaks
This is not the share of all homeowners currently delinquent. It is the share of previously current mortgage balances slipping into early delinquency. That quarterly flow has reached its highest level since roughly 2015, while the annualized flow into 90 plus day mortgage delinquency rose to 1.52% from 1.29% a year ago.
Aggregate delinquency across all household debt edged down to 4.7%, so this is not yet a systemic foreclosure wave. It is an early stage deterioration in the payment households usually defend longest.
Why It Is Happening
Most households miss the mortgage only after the rest of the balance sheet has already been used as a shock absorber. Savings are depleted, credit card balances revolve, auto and student loan payments slip, discretionary spending is cut and home equity is tapped.
In Q2, credit card balances rose $21 billion, auto debt rose $28 billion and HELOC balances increased for the 17th consecutive quarter to $459 billion. New auto and credit card delinquencies also remain elevated. The direction suggests that a growing share of households is using increasingly expensive or secured credit to preserve monthly cash flow. Once mortgage payments begin slipping, financial stress has moved considerably higher in the payment hierarchy.
The squeeze is not mainly that every fixed rate mortgage suddenly repriced. It is the entire household payment stack. Property taxes and insurance can raise escrow payments even when the mortgage rate is fixed, while food, utilities, fuel, medical costs, auto debt, credit card interest and student loans all compete for the same income.
July CPI remained 3.4% above last year, with energy up 14.7% and gasoline up 24.6%. At the same time, payrolls fell 23,000, the labor force contracted by 264,000, participation has fallen 0.7 percentage point since January and aggregate private hours were flat. Higher unavoidable costs combined with weaker income creation is the cleanest explanation for why mortgage stress is now emerging.
Why It Matters Now
Many early delinquencies will still cure. The latest New York Fed chart shows roughly 42% of mortgages already 30 to 60 days late returning to current status, while about 16% progressed to 90 plus days late. But a rising inflow keeps replenishing the pool of borrowers at risk. The New York Fed has also found that recent mortgage deterioration is concentrated in lower income areas and places where home prices are falling, precisely where borrowers have less ability to refinance, sell or extract equity.
The real warning is the timing. This is happening before a broad unemployment surge, not after one. If hiring, hours and full time employment continue weakening, the next stage will not merely be more late credit cards. It will be more households deciding which essential obligation they can afford to miss.
Mortgage delinquency is therefore not the beginning of consumer stress. It is evidence that stress which began elsewhere is finally reaching the home.
— EndGame Macro (@onechancefreedm) August 12, 2026
Student loan delinquency rates look better on paper, but the New York Fed notes they are distorted by the re-reporting of defaulted loans.
Day to day, people juggle a car payment and a card balance, then skip the retirement plan to make it work, even as Fidelity reports record average 401(k) balances.
Workers who repay student loans may qualify for an employer retirement match on their debt payments, even if they cannot afford regular 401(k) contributions.
The retirement benefits access and participation data add context: 72% of private-sector workers had access to a plan in March 2026, but only 52% participated.
The risk does not end after workers build a retirement balance. Vanguard found that retirement money in an IRA could sit in cash for years after a 401(k) rollover.
What You Should Do With These Numbers
National totals don’t pay your bills, but they do tell you where the pressure is building.
The pressure is in variable-rate, unsecured debt, and the September rate hike added to it. If you carry any card balance, this is a good month for an honest look.
- Pull your free reports at the official site for free credit reports and check for old charged-off accounts. They count against you even if you forgot them.
- List every card by interest rate and send every extra dollar to the highest one.
- If you have a HELOC, check whether its rate is variable. Most are, and they just got more expensive. Ask your lender whether part of the balance can be converted to a fixed rate.
The Number We’d Tape to the Fridge
Paying off a balance is only half the picture. The other half is what minimum payments would have cost. Paying only the minimum on a balance like $19,400 can stretch repayment over many years and add thousands of dollars in interest, compared with a fixed monthly payment that clears the debt in a few years.
The national numbers point the same way. The $13.1 trillion in mortgage debt is mostly boring, secured borrowing at lower rates. The $1.26 trillion on credit cards is expensive, unsecured, and growing. For households carrying both, the smaller balance usually deserves attention first, because it costs far more for every dollar borrowed.
For homeowners who have already cleared expensive debt and built a cash reserve, a mortgage recast may reduce the required monthly payment without a new loan. Before choosing one, it is worth comparing that lower payment with the interest saved by putting the same money toward extra principal payments instead.
Frequently Asked Questions
1. Where does the New York Fed get these numbers?
From its Consumer Credit Panel, an anonymized sample built from Equifax credit report data covering individuals across the country. It measures what appears on credit reports, not bank balance sheets.
2. How long can a charged-off debt stay on my credit report?
Generally, up to seven years from the date the account first went delinquent, under the Fair Credit Reporting Act.
3. Does paying a charged-off account remove it from my report?
No. The account updates to show it was paid, which lenders view more favorably, but the charge-off remains until the seven-year period ends.
4. Must my card issuer warn me before raising my rate?
For most rate increases, issuers must give 45 days’ notice. Variable rates that rise because the prime rate moved are the exception.
5. Do HELOCs count as mortgage debt in these figures?
No. The New York Fed reports home equity lines separately, which is why the $459 billion appears on its own line.